

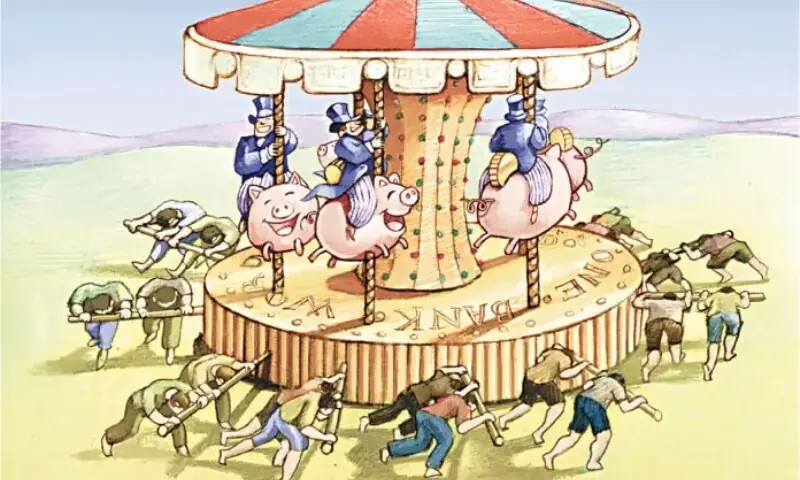

Pakistan has produced remarkably successful business families. Across textiles, cement, fertiliser, pharmaceuticals, automobiles, banking, property and energy, entrepreneurs have built substantial enterprises and considerable fortunes over several generations.
Yet one question is rarely asked in Islamabad’s boardrooms or Karachi’s drawing rooms: where are Pakistan’s multinationals? Where are the Pakistani companies acquiring British businesses, opening factories in Europe, building brands in North America, or buying technology firms capable of taking on established global corporations? For a country with more than seven decades of industrial history, the list is strikingly short.
There is a wide gulf between building a company that succeeds in Pakistan and building one that can win anywhere in the world — and Pakistan has, for the most part, only managed the first.
Why can’t our business champions compete abroad when they are successful locally?
Exports are not entrepreneurship
Pakistan has a genuine export tradition: textiles, sporting goods, surgical instruments, rice and leather goods reach markets worldwide. But shipping products abroad is a different achievement from building companies abroad. A more advanced economy exports not just goods, but capital, brands, intellectual property and management talent.
The scale of the gap is stark. According to the UN Conference on Trade and Development’s World Investment Report 2025, Pakistan recorded outward foreign direct investment of just $153 million in 2024, against inward FDI of $2.57 billion — a ratio of roughly one to seventeen.
There are exceptions. Lucky Cement has built manufacturing operations in Iraq and the Democratic Republic of Congo, proof that Pakistani industrial groups can invest and compete overseas. The question, then, is not whether Pakistani firms can internationalise, but why so few do.
Why doesn’t enterprise travel like wealth?
There is a telling contradiction among parts of Pakistan’s business elite, for whom international diversification is already familiar: property abroad, foreign education for their children, overseas residency. None of that is objectionable. But buying a flat in London or Dubai is a fundamentally different act from building a company there since property preserves wealth, but enterprise tests capability.
Taking a business into Britain, Europe or North America means competing where decades of domestic advantage count for little: unfamiliar regulators, higher costs, sophisticated customers, entrenched competitors, exacting standards of governance. Family reputation carries no weight there, and political connections at home become irrelevant. The business must win on fundamentals alone — productivity, innovation, management, execution. That is why international expansion is the clearest test of whether success is genuinely transferable, or merely local.
It would be unfair to suggest Pakistani industrialists have prospered through protection or connections alone. Building a major company in Pakistan is genuinely hard: political instability, energy shortages, currency depreciation, expensive financing, inconsistent regulation and repeated economic crises all take their toll. That takes real resilience.
But resilience at home does not prove competitiveness abroad. Some industries benefit from import barriers, cheap labour, concentrated markets, licences or long-established networks — advantages that simply do not travel. None of this invalidates domestic success, nor does it prove global competitiveness.
The experience of Pakistanis abroad offers a useful contrast. Pakistani-origin entrepreneurs and technology professionals have built considerable success in Britain, North America and the Gulf, often without inherited advantage. They started with qualifications, savings or simply an idea, in markets offering no protection and no influential contacts. The lesson is that Pakistan does not lack entrepreneurial talent. It lacks the environment, and the ambition, to turn that talent into globally competitive enterprises at home.
Producing MNCs
For decades, Pakistan’s economic debate has rightly focused on attracting foreign direct investment — international companies creating jobs and transferring technology. That objective remains sound. But it should be matched by an equally serious question: how do we build Pakistani companies capable of investing in the rest of the world?
The strongest economies do both: they draw in international capital while their own firms expand overseas, acquire businesses and grow global brands.
A challenge to the next generation
The next generation of Pakistan’s established business families has a genuine opportunity. Many inherit capital, industrial platforms, networks and infrastructure that took decades to build. Preserving that inheritance is responsible stewardship — but it should not be the limit of ambition.
If you inherit a textile business, why remain solely a supplier to international brands rather than building or acquiring one? If you inherit a pharmaceutical company, why should Pakistan remain its only serious market? If your family controls an industrial group, why not acquire technology or distribution networks abroad? And why does a house in Notting Hill count for more than a company headquartered there?
Imagine Pakistani firms as routine bidders for British, European and North American businesses, brands recognised internationally, and technology companies employing thousands across continents — a genuine shift in the country’s economic confidence.
But business cannot carry this alone. Policymakers must distinguish between capital flight and productive outward investment. Moving personal wealth abroad to protect it is one thing; a Pakistani company investing overseas to acquire customers, technology or productive capacity is quite another — and, done well, can return dividends, expertise and networks to Pakistan’s own economy. Commercial diplomacy should ask not only how to attract foreign investment, but how to help Pakistani companies become international ones.
The writer is the CEO of Sentinel Group
Published in Dawn, The Business and Finance Weekly, September 21st, 2026