

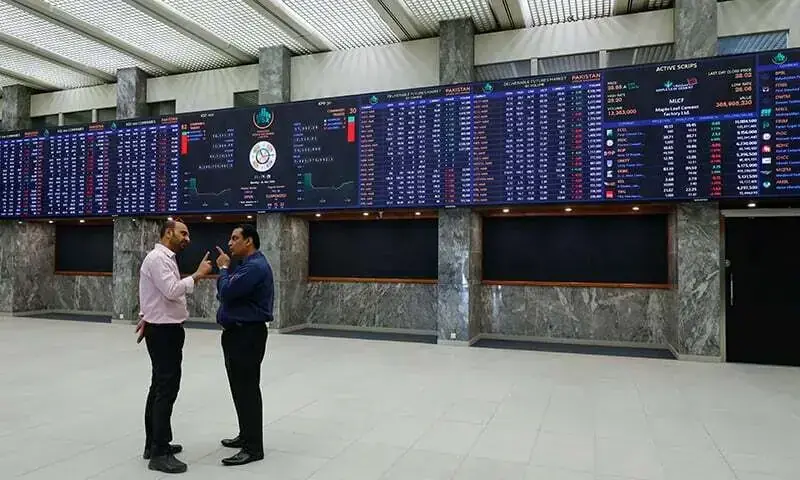
KARACHI: Extending last week’s mild recovery rally, driven by easing oil prices, the Pakistan Stock Exchange (PSX) on Monday continued to attract buying interest in selective sectors, helping the benchmark KSE-100 index close in the green, though profit-taking towards the end of the session trimmed early gains.
Topline Securities Ltd said the bulls staged a modest comeback at the bourse, as easing international oil prices and signs of potential US-Iran de-escalation provided a much-needed breather for investor sentiment.
The index opened on a strong note, extending its early gains to an intraday high of 848 points at 171,732.62, before profit-taking trimmed the gains. The index eventually settled at 171,153.17, up 268.58 points or 0.16 per cent.
The cooling oil prices offered relief to investors, easing concerns over inflationary pressures, the external account and overall macroeconomic stability. Meanwhile, ongoing diplomatic efforts to de-escalate tensions between the US and Iran further improved risk appetite.
On the index front, Lucky Cement, Attock Refinery, Fauji Fertiliser, Mari Energies, and Engro Fertiliser remained the major contributors, collectively adding approximately 254 points to the index.
Ali Najib, Deputy Head of Trading at Arif Habib Ltd, said investor sentiment remained mixed amid falling oil prices, as expectations of additional Saudi crude supply eased supply concerns. However, renewed tensions between Saudi Arabia and Iran-backed Houthi forces kept sentiment cautious.
On the sectoral front, power generation rose 5.1pc year-on-year to 14,943 GWh in August, while generation costs increased 38pc to Rs10.01 per kWh, prompting Discos to seek a Rs1.73 per kWh fuel cost adjustment.
Investor participation improved, with trading volume rising 20.23pc to 692.8 million shares. However, traded value dipped 10.3pc to Rs20.1bn. Tasdeeq Information emerged as the volume leader with 119m shares.
Analysts expect the market to remain volatile, with selective buying likely if geopolitical tensions ease and oil prices trend lower. However, elevated energy prices, external-sector risks and the upcoming IMF review will remain key drivers of market direction.
Published in Dawn, September 22nd, 2026